The short version
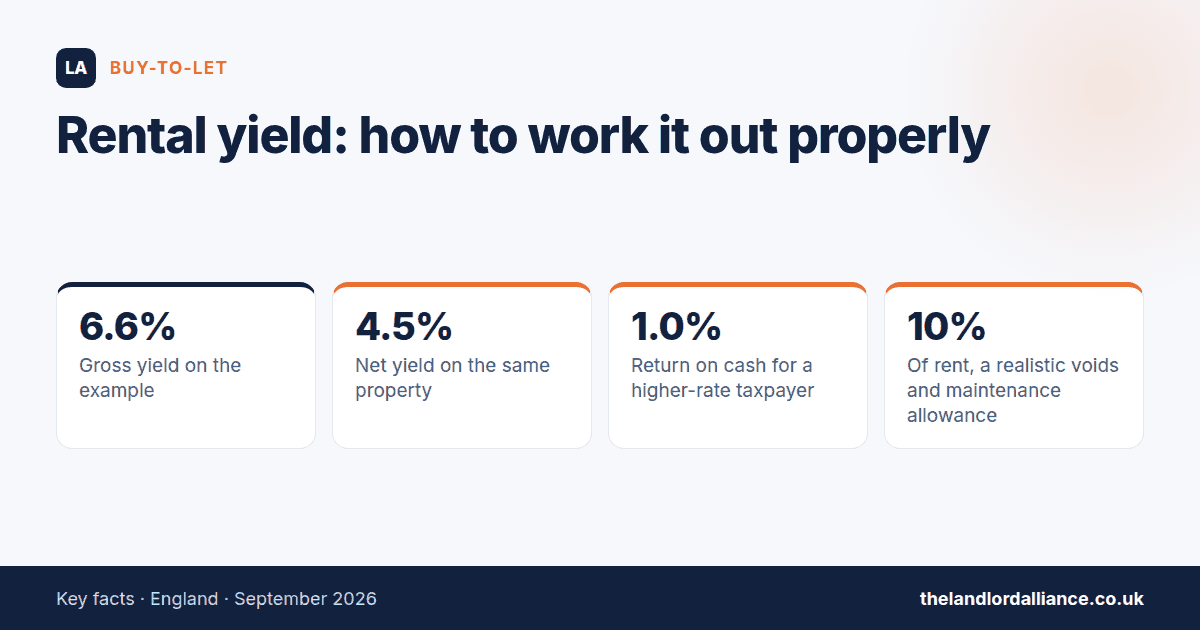
Gross yield is rent divided by price. It is the number every listing quotes and it tells you almost nothing, because it ignores every cost between the tenant paying and money reaching you. Net yield takes running costs off. Return on cash — what you actually earned, divided by what you actually put in — is the only one that answers the question you are really asking, and it is the one nobody advertises. On the worked example below the same flat shows a 6.6% gross yield, a 4.5% net yield, and a return on cash of either 4.5% or 1.0% depending on nothing more than the owner’s tax band.
The three calculations
| Measure | Formula | What it is good for |
|---|---|---|
| Gross yield | Annual rent ÷ purchase price | Comparing areas quickly. Nothing else. |
| Net yield | (Annual rent − running costs) ÷ purchase price | Comparing properties on a like-for-like basis, ignoring how they are financed. |
| Return on cash | Annual cash after everything ÷ cash actually invested | Deciding whether to buy this deal, with this mortgage, as this taxpayer. |
Worked three ways
A £200,000 flat, let at £1,100 a month, bought with a 25% deposit on an interest-only mortgage at 5%.
Gross yield
£13,200 ÷ £200,000 = 6.6%. This is the number an agent quotes. It assumes the property is let every day of the year, never needs repairing, has no insurance, and pays no tax.
Net yield
| Annual rent | £13,200 |
| Insurance, certificates, accountancy | −£800 |
| Maintenance and voids at 10% of rent | −£1,320 |
| Ground rent and service charge | −£1,200 |
| Net income | £9,880 |
| Net yield | 4.9% |
Return on cash
| Basic-rate taxpayer | Higher-rate taxpayer | |
|---|---|---|
| Net income (as above, self-managed) | £9,880 | £9,880 |
| Mortgage interest on £150,000 at 5% | −£7,500 | −£7,500 |
| Income tax after the Section 24 credit | −£716 | −£2,932 |
| Cash in your pocket | £1,664 | −£552 |
| Cash invested (deposit, stamp duty, legals) | £63,500 | £63,500 |
| Return on cash | 2.6% | Negative |
That is the point of doing this properly. A 6.6% gross yield looks like a good deal. The same property loses a higher-rate taxpayer money every month once service charges, realistic voids and tax are in the numbers. Nothing about the property changed — only the honesty of the calculation.
What yield calculations leave out
- Voids. Since May 2026 a tenant can leave on two months’ notice at any point, so assuming 100% occupancy is no longer even optimistic. Allow at least a few weeks a year.
- Ground rent and service charges on leasehold, which can be several thousand pounds and rise faster than rent.
- Major works. A section 20 bill on a leasehold flat can be five figures and arrive with little warning.
- Compliance. Gas certificate annually, EICR every five years, EPC every ten, plus any remedial work they identify.
- Tax. The single largest omission. A calculation that stops before tax is measuring the property, not your return.
- Your time. Self-managing is not free; it is unpaid. Cost it at whatever your time is worth if you would rather not do it.
What a good yield looks like
There is no national answer, because yield and capital growth trade off against each other geographically. High-yield areas tend to be lower-growth; low-yield areas are usually being priced for growth that may or may not arrive.
The more useful test is whether the deal survives stress. Take your return on cash and re-run it with the mortgage rate two points higher, two months of void instead of a few weeks, and a £3,000 repair. If it is still positive, the yield is adequate whatever the number says. If it is not, no amount of gross yield will save it — and a deal that only works on capital growth is a bet on the market rather than an investment in a rental business.
Read next
What is a good rental yield in the UK?
It depends entirely on the area and on your tax position. A better question is whether the return on cash survives a two-point rate rise, two months of void and a £3,000 repair. If it does, it is good enough.
Should I use the purchase price or the current value?
Purchase price tells you whether the original decision was sound. Current value tells you whether continuing to hold beats selling and redeploying the equity. Both are useful; be clear which question you are answering.
Does yield include the mortgage?
Gross and net yield do not — they measure the property. Return on cash does, because it measures your position.
How much should I allow for voids and maintenance?
10% of rent combined is a common working assumption, and it is a floor rather than a ceiling on an older property.
Why do agents quote gross yield?
Because it is the largest of the three numbers and it is the only one they can calculate without knowing your finances.
Is a high yield always better?
No. High-yield areas typically show lower capital growth and can carry higher management intensity. The right yield is the one attached to a property you can hold through a bad five years.
Sources. Worked examples use 2026/27 tax rates and allowances, SDLT residential rates including the 5% additional property surcharge, and the Section 24 finance cost credit at 20%. See landlord tax for the underlying figures. Checked 8 September 2026.
Related: Buy-to-let · All guides · Free calculators